If you’re paid every two weeks, choose a challenge with one step per paycheck, or save two weeks of a weekly challenge at each paycheck. This guide gives five ideas that fit biweekly pay: a count-up with 26 steps, a flat amount, a percentage that rises, a share of a raise and a round-up transfer. It also shows how to handle the year that has a 27th paycheck.

Every total below is what the steps add up to if you complete every one. It isn’t a prediction, and every amount is an example.
Why weekly charts don’t line up with biweekly pay
Most savings charts count weeks. If you’re paid every two weeks, you only get 26 paychecks in most years, so each paycheck has to cover two weeks of the chart. Payroll tables count 26 pay periods a year for biweekly pay, compared with 52 for weekly pay (Publication 15-T (2026), Federal Income Tax Withholding Methods).
You have two options. You can pick a challenge built around paychecks, as the first five ideas below are. Or you can pair the weeks of a weekly challenge, so paycheck 1 covers weeks 1 and 2, paycheck 2 covers weeks 3 and 4, and so on. For the 52-week count-up at a $1 step, that means $3 at paycheck 1, $7 at paycheck 2 and $103 at paycheck 26.
Do you have 26 paychecks or 27?
A biweekly schedule has 26 paydays in most years. It has 27 in a year whose first payday falls on January 1, or on January 1 or 2 in a leap year. That’s because 27 paydays 14 days apart fit into 365 days only if the first one lands on the first day. Check your first payday of the year.
The challenges below assume 26 paychecks. In a 27-payday year, treat the extra paycheck as free room: leave it alone, add a small amount to your challenge place or use it to catch up on a missed step.
Find your safe amount per paycheck
Look at your account balance the day before each of your last three paydays and subtract bills still due. Take the lowest of the three and round down. That’s your safe amount per paycheck. Divide by two for your safe weekly amount.

EXAMPLE: Nia is paid every two weeks and takes home $1,600. The day before payday, the balance was $140, $90 and $120, so Nia plans on $70 a paycheck, which is $35 a week. A size passes if its average week is at or below $35 and its biggest paycheck is at or below $70.
Five biweekly challenge ideas
Each size is defined by the average week: low is up to about $13, medium is about $14 to $30 and high is above about $30. These bands are our own rule of thumb, not a standard.
| Idea | Rule | Total if finished (low / medium / high) |
|---|---|---|
| Biweekly count-up | Add one step at each of 26 paychecks | $351 / $1,053 / $1,755 |
| Same amount every paycheck | Move a flat amount each payday | $390 / $910 / $1,950 |
| Percent step-up | Save a share of take-home pay and raise it | Depends on your pay |
| Save the raise | Save a share of a take-home pay increase | $650 / $1,300 / $1,950 |
| Round-up transfer | Round card purchases up and move the difference | Depends on your purchases |
The biweekly count-up
Paycheck 1 saves one step, paycheck 2 saves two steps, and paycheck 26 saves 26 steps. The step is $1 at low, $3 at medium and $5 at high. The biggest paychecks are $26, $78 and $130.
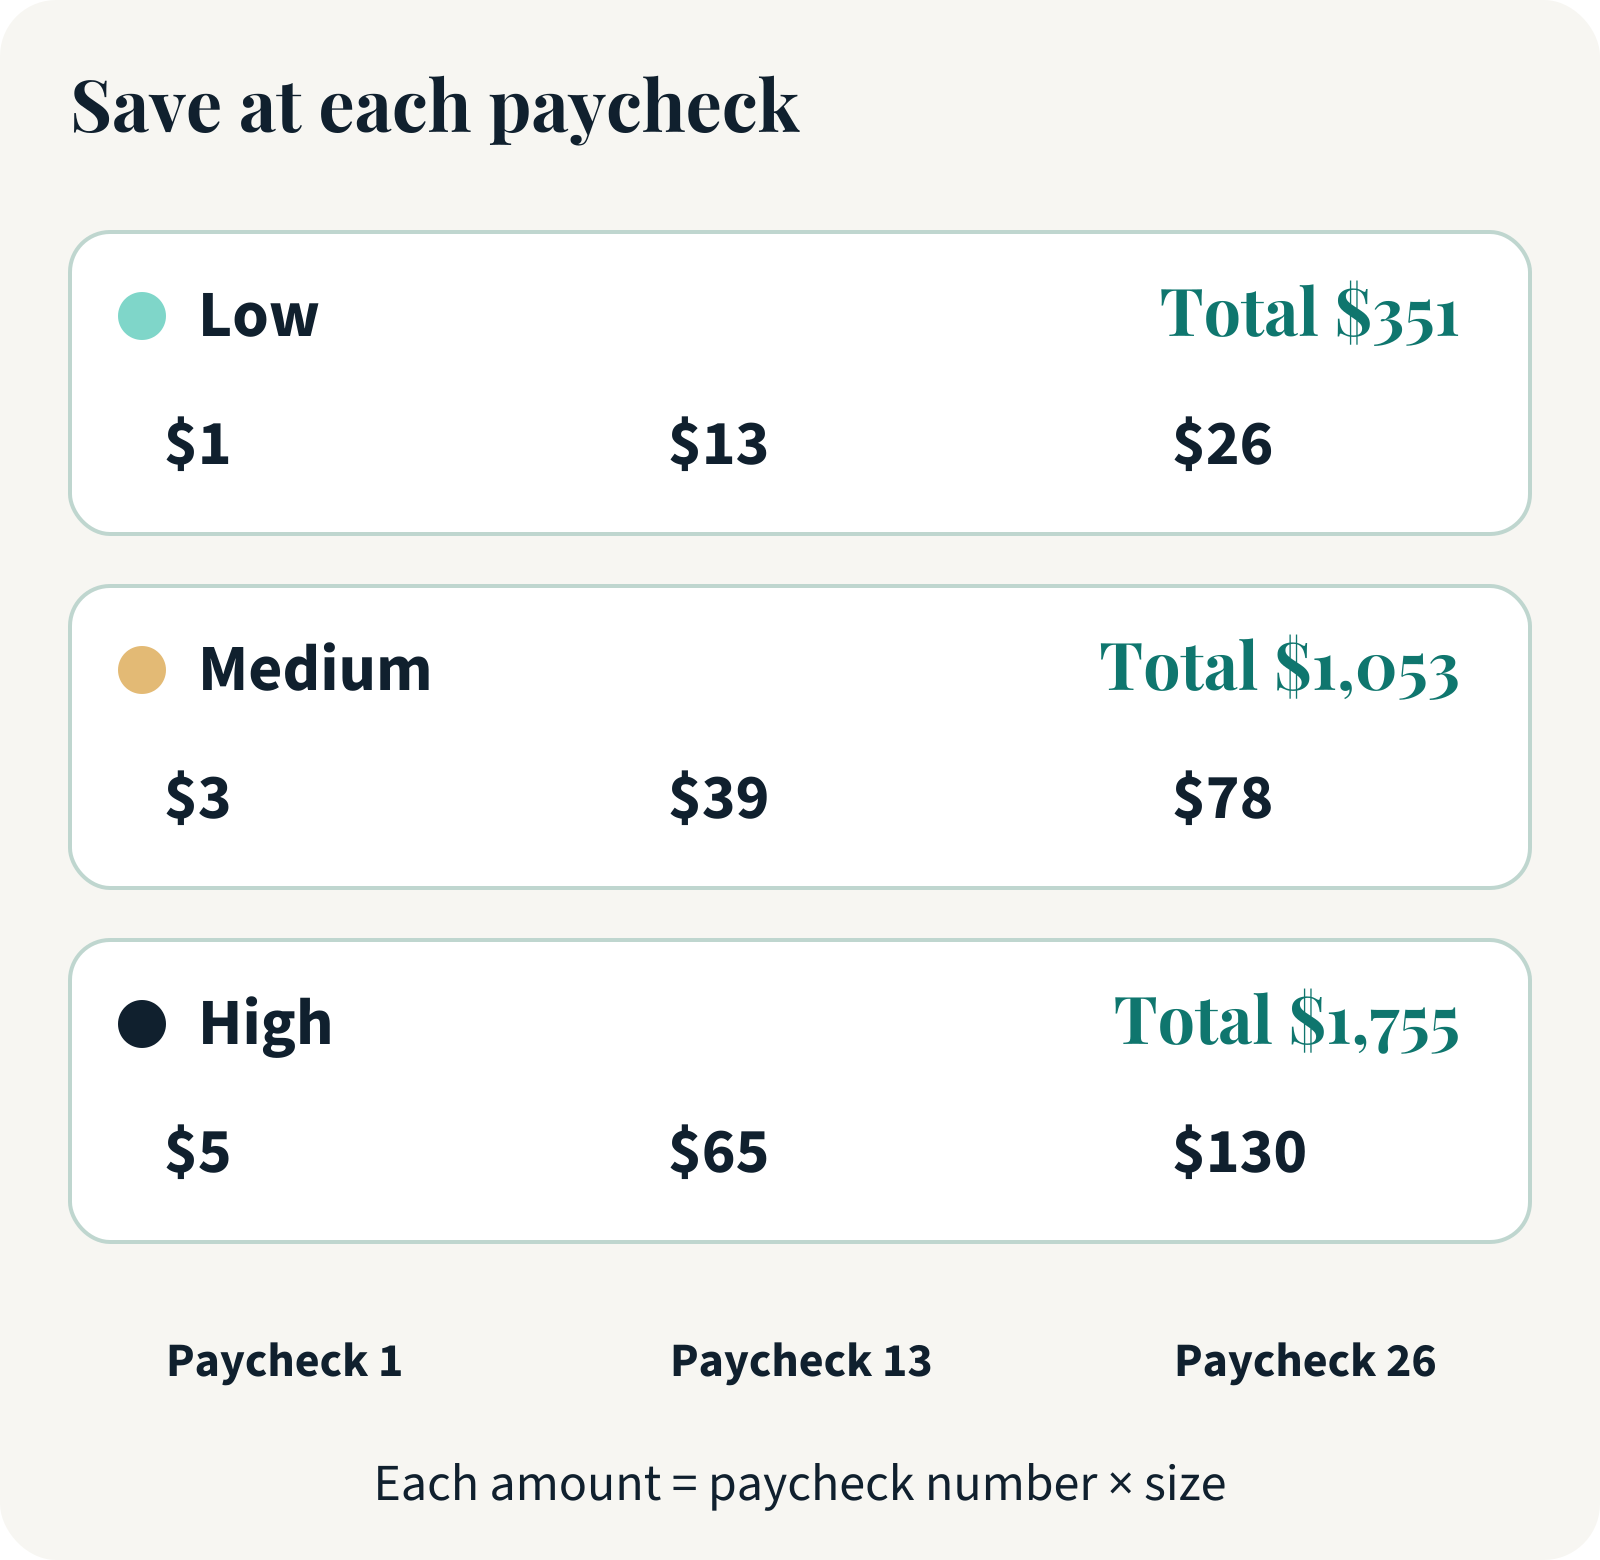
Nia’s average-week test passes at all three sizes ($6.75, $20.25 and $33.75 against $35). The biggest-paycheck test is different. The last paycheck is $26 at low, which fits within $70, and $78 at medium, which doesn’t. Nia picks low, and plans to look at a larger size next time.
The same amount every paycheck
The plainest idea: move one amount at each payday. A single recurring transfer does the whole job. The amount is $15 at low, $35 at medium and $75 at high, so over 26 paychecks the totals are $390, $910 and $1,950. In a 27-payday year they’re $405, $945 and $2,025.
There’s no hard week, so if the average passes, the biggest paycheck does too. It suits you if you want to automate the whole thing.
The percent step-up
Save a share of each paycheck, and raise the share by one point every six or seven paychecks. Because the amount follows your pay, it suits people whose paychecks change.
EXAMPLE: Nia takes home $1,600 a paycheck. Nia saves 2 percent for the first seven paychecks, 3 percent for the next seven, then 4 percent for six and 5 percent for the last six. The saves are $32, $48, $64 and $80. Together that’s $224 plus $336 plus $384 plus $480, which adds up to $1,424. The biggest paycheck is $80, which is above Nia’s $70, so Nia would stop at 4 percent.
Save the raise
When your take-home pay goes up, save a share of the increase before you get used to it. If take-home pay rises by $100 a paycheck, saving a quarter is $25 a paycheck, half is $50 and three-quarters is $75. Over 26 paychecks that’s $650, $1,300 or $1,950. Use the change in the amount that lands in your account, not the change before taxes.
The round-up transfer
Each time you pay with a card, note how far the purchase is from the next round amount. At the end of each week, move the total of the differences. If you’re paid every two weeks, you can move it at each paycheck. In one example week of eight purchases, rounding up to the next $1 gives $4.15, the next $2 gives $7.15 and the next $5 gives $14.15. Real weeks will differ, so the total depends on what you buy.
A payday routine that works
Give each paycheck a small routine. A review of 94 tests looked at plans in the form “If situation Y, then I will do X.” On average, they had a medium-to-large positive effect on reaching goals (Implementation intentions and goal achievement: A meta-analysis of effects and processes). That review looked at goals in general, not at saving in particular, but a rule like “If it’s payday, then I move my step before I spend anything” is easy to try.
The U.S. Consumer Financial Protection Bureau says recurring transfers from checking to savings are often one of the easiest ways to save consistently. Some employers let you split a direct deposit between accounts, and you should watch your balance so an automatic transfer doesn’t trigger overdraft fees (An essential guide to building an emergency fund).
When your pay changes or you miss a paycheck
A missed paycheck is information, not failure. You can skip the step, catch up in small pieces, slide the dates, merge two steps or shrink to a smaller size. If your pay drops, rerun the safe-amount check from this guide with your new numbers. How to Restart a Savings Challenge After You Fall Behind shows each option with the arithmetic.
Common questions about biweekly savings challenges
What is the best biweekly savings challenge for beginners?
A flat amount per paycheck at the low size, such as $15, is the simplest. It has no hard week. See Low-Budget Savings Challenges for Beginners: Start With $5 a Week for more starting points.
Can I do the 52-week challenge if I’m paid biweekly?
Yes. Save two weeks of steps at each paycheck. At a $1 step, that’s $3 at the first paycheck and $103 at the last. The 52-Week Savings Challenge: Low, Medium and Reverse Versions Explained shows the full table.
What if I get a 27th paycheck in a year?
Treat it as free room. Leave it alone, add a small amount to your challenge place, or use it to catch up on a missed step.
Should I save from every paycheck?
You can. Some people skip a paycheck with a known big bill and use a pause rule instead. Write the rule before you need it.
What if my pay varies from paycheck to paycheck?
The percent step-up follows your pay, and the windfall rule asks for nothing in a month with no extra money.
Your next step

Count your paychecks for the year, check whether your first payday is January 1, and write your safe amount per paycheck. Then pick one idea and write the first four paychecks with dates. The free Savings Challenge Picker can narrow the list, and the Savings Challenge Tracker Pack has a paycheck-by-paycheck list if you’d like a ready-made one.
Sources and tools used in this guide
Checked on October 12, 2026. Dollar amounts in the examples are illustrative and are not forecasts, unless a source is named.
- Publication 15-T (2026), Federal Income Tax Withholding Methods, Internal Revenue Service
- “Implementation intentions and goal achievement: A meta-analysis of effects and processes,” Gollwitzer and Sheeran, Advances in Experimental Social Psychology, 2006
- “An essential guide to building an emergency fund,” Consumer Financial Protection Bureau
This guide is general education, not financial advice. See our Disclaimer.